
Budgeting for unexpected remodel costs means setting aside a contingency fund of 10%–20% of your total renovation budget to cover surprises like hidden damage, code upgrades, or material price changes. Most homeowners plan for what they can see: cabinets, tile, fixtures. They forget what lives behind the walls. A single discovery of mold, asbestos, or outdated wiring can add thousands to a project that looked straightforward on paper. Redfin, PNC, and remodeling industry authorities all point to the same root cause of blown budgets: no structured contingency plan from day one.
How to budget for unexpected remodel costs by project type
The right contingency percentage is not one-size-fits-all. It depends on your project scope, the age of your home, and how much of the mechanical and structural systems you are touching.
Industry guidance breaks projects into four risk tiers:
- Cosmetic updates (paint, flooring, fixtures): 5%–8% contingency
- Kitchen or bathroom remodels in post-1980 homes: 10%–15% contingency
- Full system replacements (HVAC, plumbing, electrical): 15%–20% contingency
- Structural modifications or older homes: up to 20%–25% contingency
Higher risk triggers a larger buffer. That logic is straightforward. What trips homeowners up is applying a cosmetic-project percentage to a project that is actually a full systems overhaul.
| Project type | Typical contingency | Key risk factors |
|---|---|---|
| Cosmetic refresh | 5%–8% | Low; visible scope only |
| Kitchen/bath remodel (post-1980) | 10%–15% | Hidden plumbing, tile substrate |
| Full system replacement | 15%–20% | HVAC, electrical, plumbing |
| Structural or pre-1980 home | 20%–25% | Code gaps, hazardous materials |
A practical example: an $80,000 kitchen and bath remodel in a 1975 Houston home should carry a contingency fund of $16,000–$20,000. That is not pessimism. That is math based on what contractors actually find behind walls in older homes.
Pro Tip: Age your contingency percentage alongside your home. A 1960s house with original plumbing deserves a 25% buffer, not a 10% one.
How to build a renovation budget with contingency built in
A well-structured renovation budget has three distinct layers, not one lump sum. Separating these layers improves financial stability and prevents the most common mistake: raiding the contingency fund to pay for upgrades.
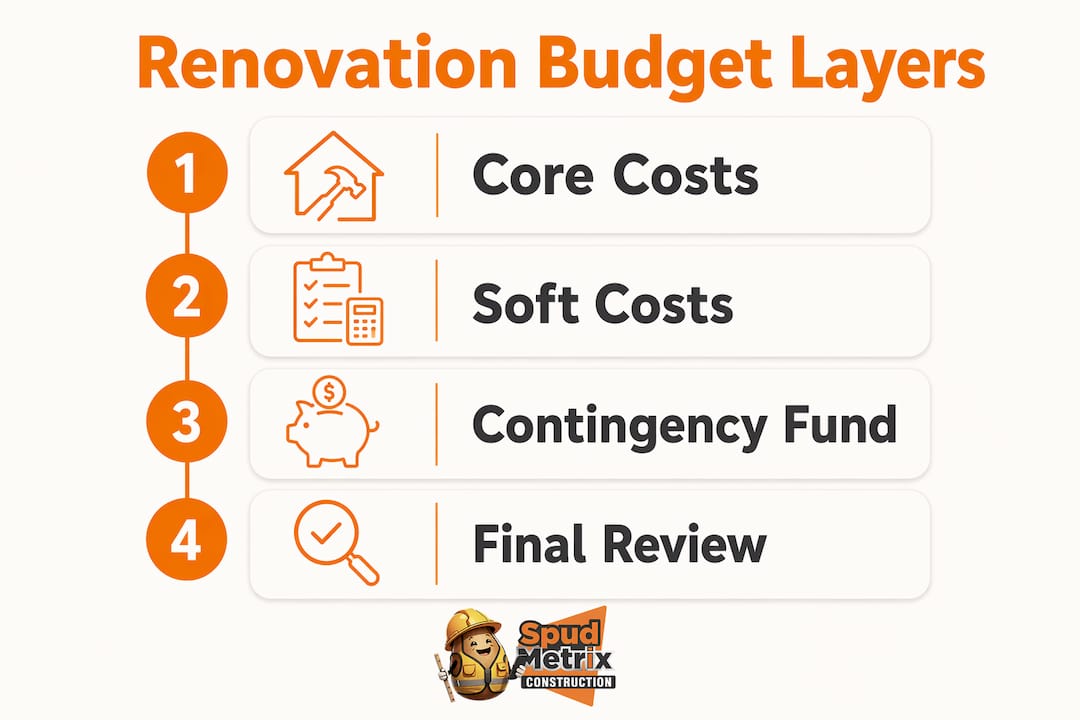
Layer 1: Core project costs. This is the direct construction work. Labor, materials, subcontractors, and equipment rentals all belong here. Get itemized bids, not ballpark figures. Reading a written remodeling estimate line by line tells you exactly what is and is not included.
Layer 2: Supporting costs (soft costs). These are the expenses that do not show up on a contractor’s bid but still come out of your pocket.
- Permit fees and inspection costs
- Architect or designer fees
- Temporary housing or storage if you are displaced
- Waste removal and demolition disposal
- Utility reconnection fees
Hidden costs like mold remediation, permitting, and temporary housing can significantly impact budgets when left unplanned. Soft costs routinely run 10%–15% of the core construction budget on top of the base bid.
Layer 3: Contingency fund. This layer is structural, not optional. It sits in a separate mental account and covers only true unknowns: things discovered during demolition, code-required upgrades, or material substitutions forced by supply issues.
Pro Tip: Finalize all design selections and material choices before demolition begins. Completing selections before construction minimizes costly mid-project changes and sharpens your budget accuracy from day one.
The biggest budgeting mistake most homeowners make is underestimating soft costs and failing to allocate contingency as a separate line item. When contingency is folded into the general budget, it disappears into upgrades and overages before the first surprise even arrives.
How do you control unexpected costs during a remodel?
Controlling unexpected renovation expenses during construction requires process discipline, not just a savings buffer. The contingency fund is only useful if you govern how it gets spent.
Follow this workflow to stay in control:
Ring-fence the contingency fund. Keep it in a separate account or budget line. Categorizing contingency into named buckets (structural, finishes, permits) reduces conflicts and makes spending decisions faster and clearer.
Require written change orders for every scope change. Change orders are the leading cause of budget overruns. Mid-project changes can raise costs 15%–25% above the original scope. No verbal agreements. Every change gets a price, a signature, and a budget line before work starts.
Track spending weekly. Weekly tracking with receipts and spreadsheets supports budget visibility and helps you catch drift before it becomes a crisis. A simple spreadsheet with columns for budgeted, committed, and actual costs is enough.
Separate contingency from upgrade requests. Contingency funds must not cover owner-requested upgrades mid-project. If you decide to swap standard tile for imported stone, that cost comes from a separate upgrade budget, not the emergency reserve.
Make tradeoff decisions with data. Experienced homeowners track weekly actuals against budget and use that data to make informed tradeoffs: postpone a finish upgrade, substitute a material, or apply value engineering to recover 10%–20% of overrun costs without changing the design.
Pro Tip: Set a pre-approval threshold for contingency spending. Any single expense under $500 gets field-approved by your contractor. Anything above requires your sign-off before work proceeds.
What causes unexpected remodel expenses and how do you prevent them?
Most budget surprises fall into predictable categories. Knowing them in advance lets you prepare, not react.
- Hidden damage. Mold, rot, asbestos, and pest damage are the most common discoveries during demolition. Homes built before 1980 carry the highest risk. Budget for remediation before you open walls, not after.
- Code upgrades. Opening walls or adding square footage often triggers code compliance requirements for electrical panels, egress windows, or fire blocking. Your contractor cannot predict these until the permit review is complete.
- Material price changes. Supply chain volatility affects lumber, appliances, and specialty tile. Lock in material pricing early and order long-lead items before demolition starts. Early procurement of long-lead items reduces schedule and cost pressure significantly.
- Permit delays. A delayed permit stalls your contractor and can trigger escalation clauses in labor contracts. Submit permits as early as possible. Understanding why permit costs appear in estimates helps you plan for both the fees and the timeline.
- Scope creep. This is the silent budget killer. A small addition here, a finish upgrade there, and suddenly the project is 20% over budget with no clear cause. Vague contract language and verbal agreements make scope creep nearly impossible to track or dispute.
The fix for most of these triggers is front-loaded planning. Finalize your scope before signing a contract. Use a detailed interior remodel planning checklist to identify unknown conditions early. Avoid any contractor who resists putting changes in writing.
Key Takeaways
Effective financial planning for renovations requires a structured contingency fund, strict governance over how that fund is spent, and front-loaded planning to reduce surprises before demolition begins.
| Point | Details |
|---|---|
| Set the right contingency percentage | Use 5%–8% for cosmetic work, up to 20%–25% for structural or pre-1980 homes. |
| Build a three-layer budget | Separate core costs, soft costs, and contingency into distinct budget lines. |
| Require written change orders | Every scope change needs a price and a signature before work begins. |
| Track actuals weekly | Compare budgeted versus actual costs weekly to catch overruns early. |
| Protect the contingency fund | Never spend contingency on upgrades; reserve it strictly for true unknowns. |
What I’ve learned about contingency budgets after years of remodeling projects
The homeowners who finish remodels on budget are not the ones who got lucky. They are the ones who treated the contingency fund as untouchable from day one.
The most common mistake I see is treating contingency as a slush fund. A homeowner sees the reserve sitting there and decides it covers the upgraded countertop they always wanted. Then the inspector finds knob-and-tube wiring behind the kitchen wall, and suddenly there is no buffer left. That is not bad luck. That is a governance failure.
The second mistake is waiting until something goes wrong to look at the numbers. Budget visibility has to be a weekly habit, not a crisis response. When you track actuals against your budget every week, you make small corrections instead of big ones. You postpone a finish upgrade instead of scrambling for a home equity line at the worst possible moment.
The discipline that actually works is simple: write down every change, price every change before approving it, and keep the contingency fund in a separate mental account with a clear rule about what qualifies for it. Structural discoveries qualify. Owner upgrades do not. That one rule prevents more budget disasters than any spreadsheet formula.
If you are a property manager running multiple units, the stakes are even higher. One unplanned remediation on a rental property can wipe out months of cash flow. The remodeling project phases framework helps you anticipate where surprises cluster and build phase-specific buffers instead of one generic reserve.
— Brandon
How Spudmetrix helps Houston homeowners plan and control remodeling budgets
Spudmetrix works with Houston homeowners and property managers who want clear numbers before a single wall comes down.
Every Spudmetrix project starts with a free in-home consultation and a detailed written estimate that breaks out core costs, soft costs, and contingency recommendations by project type. There are no vague line items and no surprise invoices mid-project. Spudmetrix also handles permitting and inspections directly, which removes one of the most common sources of schedule and cost pressure. For homeowners who want to understand what belongs in a contract before signing anything, the Spudmetrix guide to remodeling contracts covers every clause that protects your budget from scope creep and verbal change orders. When the numbers matter, working with a contractor who puts everything in writing makes the difference.
FAQ
What is the standard contingency for a home remodel?
The standard contingency for a home remodel is 10%–20% of the total project budget. Higher-risk projects, such as structural work or renovations in pre-1980 homes, warrant the upper end of that range.
Should contingency funds cover upgrade requests?
No. Contingency funds should cover only true unknowns, such as hidden damage or code upgrades. Owner-requested upgrades belong in a separate budget line to preserve the contingency as a financial buffer.
What causes the most unexpected renovation expenses?
Hidden damage (mold, rot, asbestos), code compliance requirements, and mid-project scope changes are the most common causes. Early permitting and locking in material prices before demolition reduce most of these risks.
How do written change orders protect your budget?
Written, priced, and pre-approved change orders prevent verbal agreements from inflating project costs. Mid-project changes without written orders are the leading cause of budget overruns in residential remodeling.
When should I start tracking renovation spending?
Start tracking from the first deposit payment. Weekly tracking of receipts and actual costs against your budget lets you catch overruns early and make informed tradeoffs before costs spiral.