
Contractor insurance protects clients by transferring financial and legal risk from the property owner to the contractor’s insurer. When a worker gets hurt on your property, a subcontractor damages your flooring, or a completed repair fails and causes water damage months later, the right contractor insurance coverage pays the claim instead of you. Understanding how contractor insurance protects clients means knowing which policies apply, which endorsements you must require, and where the gaps are. This guide covers all three, so you walk into every project with your exposure clearly defined.
How contractor insurance protects clients from construction risks
Contractor insurance is a package of multiple policies working together. A typical small contractor package includes General Liability, Workers Compensation, Commercial Auto, and Tools coverage, with annual costs ranging from $1,800 to $8,500 depending on trade and revenue. Each policy targets a different category of risk, and each one affects you as the property owner in a specific way.
The four protections that matter most to homeowners and property managers are:
- Third-party bodily injury coverage. If a contractor’s worker or a visitor is injured on your property because of the contractor’s work, General Liability pays the medical costs and legal claims. Without this, the injured party can sue you directly.
- Property damage coverage. Accidental damage to your home, your neighbor’s fence, or your tenant’s belongings during construction falls under this coverage. Completed operations coverage extends that protection after the project is finished, covering defects that cause damage weeks or months later.
- Legal defense costs. General Liability pays attorney fees and settlements even when the claim is disputed. Legal defense alone can cost tens of thousands of dollars before a case is resolved.
- Workers Compensation. This policy covers the contractor’s employees for job-related injuries. It matters to you because an injured worker without Workers Comp coverage can sometimes pursue a claim against the property owner instead.
Pro Tip: Ask every contractor for proof of Workers Compensation coverage separately from their General Liability certificate. The two policies are distinct, and many homeowners assume one covers both.
What contract endorsements actually secure your protection?
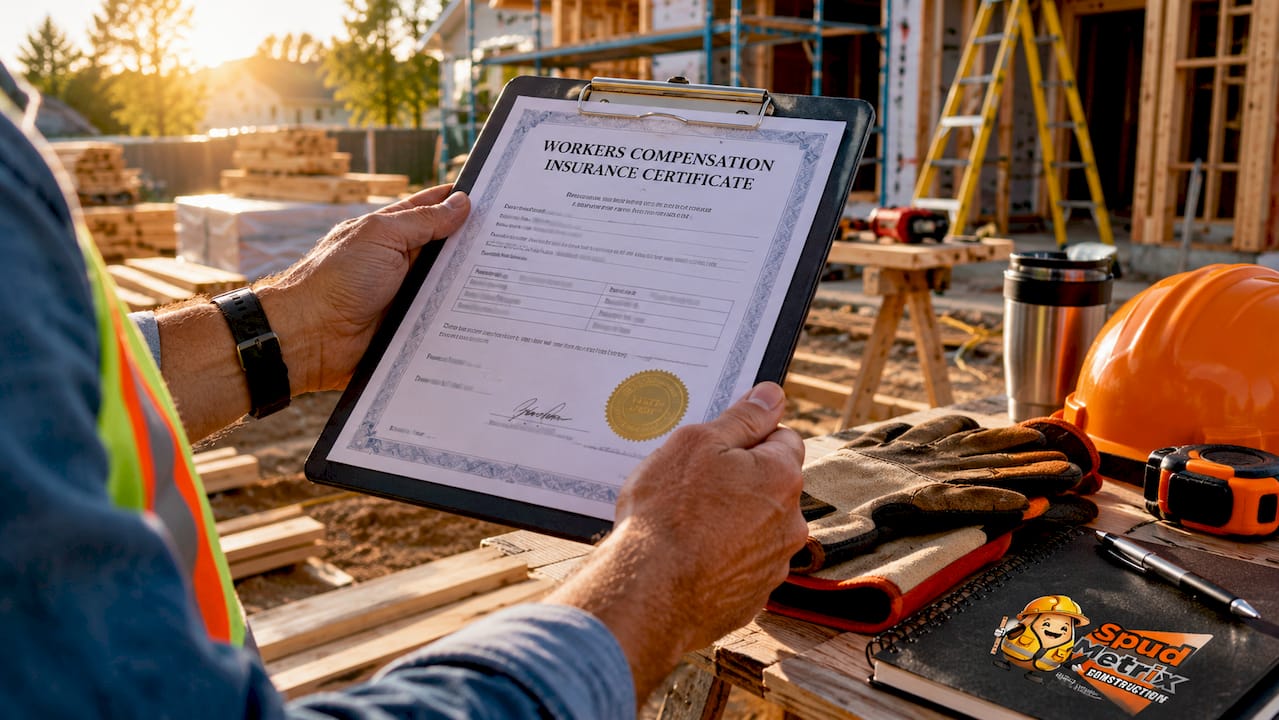
A certificate of insurance (COI) proves that a policy exists. It does not prove that you are covered. The real protection for clients lives in policy endorsements, and you must require them in writing before work begins.
Three endorsements define effective client protection in contracting:
- Additional Insured endorsement. This adds you to the contractor’s General Liability policy as a protected party. Without this endorsement, the contractor’s insurer has no obligation to defend you if a claim arises from the contractor’s work. Specify both ongoing operations and completed operations coverage in the endorsement.
- Waiver of Subrogation. After paying a claim, an insurer normally has the right to sue whoever caused the loss to recover its money. A Waiver of Subrogation removes that right, so the contractor’s insurer cannot turn around and sue you after paying out a claim on your project.
- Primary and Non-Contributory wording. This language ensures the contractor’s policy pays first on any covered claim, without pulling your own homeowner’s or property insurance into the loss. Without it, both insurers may argue over who pays, and your premiums can rise even when the contractor caused the damage.
All three must appear in the contract before the first worker sets foot on your property. Contractors need time to obtain correct endorsements from their insurer, and last-minute requests often result in missing or incorrectly worded forms.
Pro Tip: When you receive a COI, look for the specific policy form numbers CG 20 10 and CG 20 37. These form numbers confirm that the Additional Insured endorsement covers both ongoing and completed operations, not just one phase.
Some contractors carry a blanket Additional Insured endorsement, which automatically extends coverage to all clients they have contracts with. This costs the contractor 2%–5% more in premiums but eliminates delays and paperwork for you. Ask whether your contractor carries a blanket endorsement before requesting a project-specific one.
Common gaps in contractor insurance clients often miss
General Liability insurance is the foundation of contractor liability coverage, but it has real limits. Clients must verify that coverage limits match the scale of their project, because a policy with a $1 million per-occurrence limit may not be enough for a large addition or a multi-unit renovation.
The most common coverage gaps that expose homeowners and property managers include:
- Professional errors and design mistakes. Standard General Liability does not cover faulty design or professional advice. If a contractor makes a structural error based on a flawed plan, you may need to pursue a separate professional liability claim.
- Employee injuries without Workers Comp. If a contractor skips Workers Compensation coverage, an injured worker may have grounds to pursue a claim against you as the property owner.
- Underinsured contractors. A contractor with a $500,000 General Liability limit working on a $400,000 renovation leaves very little room for a major claim. Always confirm that limits are adequate for your specific project.
- Expired or lapsed policies. A COI issued in january may show active coverage that expired by march. Policies lapse when premiums go unpaid, and you will not receive automatic notice.
A certificate of insurance only proves coverage existed on the date it was issued. True client protection depends on verifying that the policy is active, the endorsements are correctly worded, and the limits are sufficient for your project scope.
Uninsured or underinsured contractors shift risk directly back to you. When a contractor cannot pay a claim, the injured party or damaged property owner looks to whoever has assets, and that is often the homeowner. Vetting insurance before signing any contract is the single most effective risk management step you can take.
Best practices for homeowners to verify contractor coverage
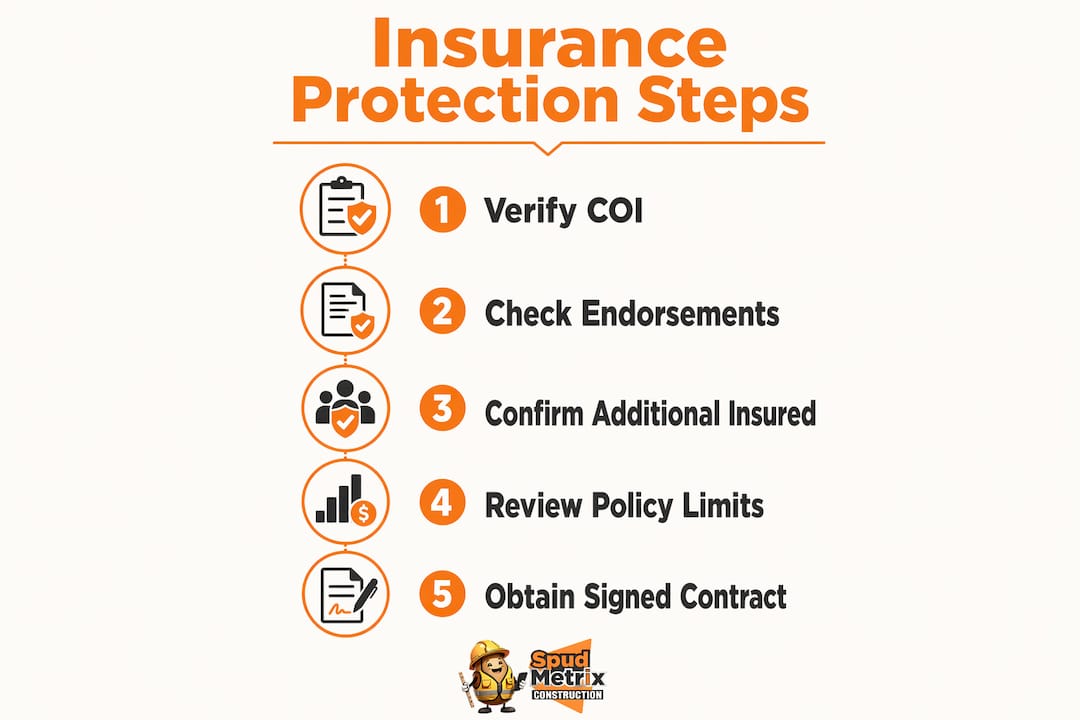
Protecting yourself through contractor insurance requires action before the project starts, not after something goes wrong. The following steps give you a clear process for every project.
- Set insurance requirements in the contract. Spell out required policy types, minimum coverage limits, and mandatory endorsements in the written contract. Include these specifications during the bidding phase so contractors can price the job with correct insurance in place.
- Request the COI and endorsement forms together. Never accept a COI alone. Ask for the actual endorsement forms attached to the policy, including the Additional Insured form and the Waiver of Subrogation.
- Hire only licensed and insured contractors. Licensing requirements vary by state, but a licensed contractor is far more likely to carry proper insurance and maintain it throughout the project.
- Confirm coverage at renewal. If your project runs longer than a few months, request an updated COI when the contractor’s policy renews. Policies typically renew annually, and a lapse mid-project leaves you exposed.
- Match limits to project size. For large renovations or new construction, consider umbrella policies or require the contractor to carry excess liability coverage above the standard General Liability limit.
- Consult your own insurance professional. Your homeowner’s or property insurance agent can review the contractor’s COI and flag gaps you might miss. This step costs nothing and can prevent significant financial loss.
| Step | When to do it | What to verify |
|---|---|---|
| Set insurance requirements | During contract drafting | Policy types, limits, endorsements |
| Request COI and endorsements | Before work starts | Active dates, form numbers, named insured |
| Confirm Workers Comp | Before first worker arrives | Separate certificate, active policy |
| Check coverage at renewal | Mid-project if over 6 months | Updated COI, no lapse in coverage |
| Review limits for large projects | At bid review stage | Per-occurrence and aggregate limits |
Reviewing contractor bids with insurance requirements already defined gives you a direct comparison across contractors. A lower bid from an uninsured contractor is never actually cheaper once you account for the risk you absorb.
Key Takeaways
Contractor insurance protects clients only when the right endorsements are in place, the limits match the project, and the contract specifies coverage requirements before work begins.
| Point | Details |
|---|---|
| COI is not enough | Always request endorsement forms alongside the certificate to confirm actual client coverage. |
| Three endorsements matter most | Require Additional Insured, Waiver of Subrogation, and Primary/Non-Contributory wording in every contract. |
| Gaps can expose you | General Liability excludes professional errors and employee injuries without Workers Comp coverage. |
| Set requirements early | Include insurance specifications during bidding so contractors have time to obtain correct endorsements. |
| Match limits to project scale | Verify per-occurrence limits are adequate; large projects may need excess or umbrella coverage. |
What I’ve learned after years of watching clients get this wrong
Most homeowners assume that asking for a certificate of insurance is enough. It is not, and I have seen that assumption cost people real money.
The pattern repeats itself. A homeowner hires a contractor, receives a COI, and feels protected. Then a worker gets hurt, or a pipe fails three months after the job is done, and the claim lands on the homeowner’s policy because the Additional Insured endorsement was never added. The contractor’s insurer has no obligation to step in. The homeowner’s premiums go up. Sometimes there is a lawsuit.
The uncomfortable truth is that the COI is a marketing document as much as it is a legal one. It tells you a policy exists. It tells you nothing about whether you are actually named on it, whether the endorsements are correctly worded, or whether the policy was still active last week.
What actually works is treating insurance the same way you treat the contract itself. Write the requirements down. Specify the form numbers. Ask for the endorsements before the first day of work, not the day before closing. Contractors who carry proper coverage will not hesitate. Contractors who push back or go quiet are telling you something important.
Property managers especially need to hear this. You are managing risk across multiple units and multiple contractors. One uninsured subcontractor on one job can create a liability that touches your entire portfolio. The red flags to watch for in contractor selection almost always include insurance gaps, and they are visible if you know where to look.
— Brandon
Spudmetrix helps you build contracts that protect you
Knowing what to require is only half the job. The other half is getting those requirements into a contract that actually holds.
Spudmetrix works with Houston homeowners and property managers to structure remodeling agreements that spell out insurance requirements clearly, including Additional Insured status, Waiver of Subrogation, and Primary/Non-Contributory language. Every project starts with a free in-home consultation and a detailed written estimate, so there are no surprises on coverage or cost. The remodeling contract guide for 2026 walks through exactly what to include before any contractor picks up a tool. If you are planning a renovation in the Houston area, Spudmetrix is ready to help you get it right from the start.
FAQ
What does contractor insurance cover for clients?
Contractor insurance covers clients for third-party bodily injury, property damage, legal defense costs, and completed operations liabilities arising from the contractor’s work. The specific coverage available to you depends on whether you are named as an Additional Insured on the contractor’s policy.
Is a certificate of insurance enough to protect me?
A COI proves a policy exists but does not confirm you are covered. True client protection requires Additional Insured endorsements attached to the contractor’s policy, specifying both ongoing and completed operations coverage.
What is an Additional Insured endorsement?
An Additional Insured endorsement adds you to the contractor’s General Liability policy as a protected party. Look for policy form numbers CG 20 10 and CG 20 37 to confirm the endorsement covers both the active construction phase and the period after the project is complete.
What happens if my contractor is uninsured?
An uninsured contractor shifts all financial risk back to you. If a worker is injured or your property is damaged, you may face direct legal claims with no contractor insurance to cover the loss, making your own homeowner’s or property insurance the only line of defense.
When should I verify contractor insurance?
Set insurance requirements during the contract and bidding phase, before any work begins. For projects lasting more than six months, request an updated COI when the contractor’s policy renews to confirm there has been no lapse in coverage.