
Contractor bonding is defined as a three-party financial guarantee in which a surety company promises a project owner that a contractor will complete the work and meet all payment obligations. The industry term is “surety bond,” and it covers three distinct roles: the contractor (the principal), the project owner (the obligee), and the surety company that backs the guarantee. Bonding is not the same as insurance. It is a credit instrument that holds the contractor financially accountable. For homeowners, property managers, and real estate investors, understanding contractor bonding explained in plain terms is the first step toward protecting any renovation or construction investment.
What does contractor bonding mean for your project?
Contractor bonding means a licensed third party has evaluated your contractor and agreed to back their performance with real money. The surety bond protects the project owner by ensuring the contractor completes the work, or the surety finances completion and pays damages up to the bond amount. That guarantee runs in your favor as the owner.
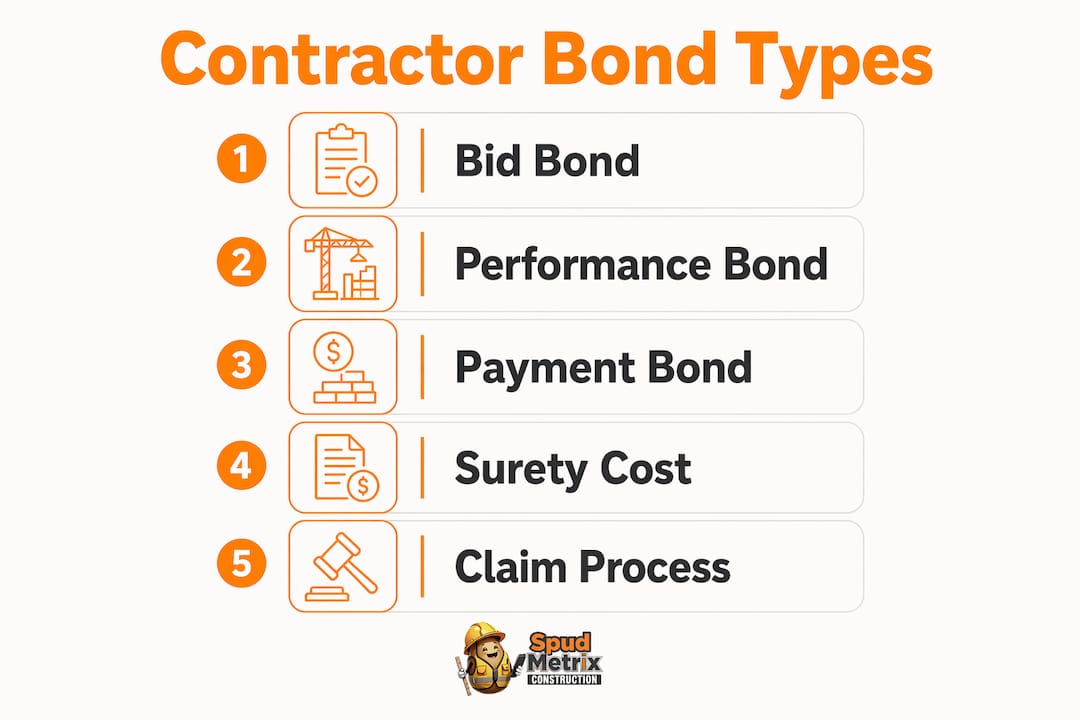
Three bond types appear most often in construction and renovation work. Each covers a different risk, and knowing which one applies to your project changes how you evaluate bids and write contracts.
| Bond type | What it guarantees | Typical use case |
|---|---|---|
| Bid bond | Contractor honors the bid and signs the contract | Competitive bidding on public or large private projects |
| Performance bond | Contractor completes the project per contract terms | Mid-size to large construction and renovation projects |
| Payment bond | Subcontractors and suppliers get paid | Projects with multiple trade contractors involved |
The Miller Act requires performance and payment bonds on all federal construction contracts over $150,000. Most states have parallel laws for public works. Private renovation projects are not legally required to carry bonds, but that does not mean you should skip them.
Why does contractor bonding matter for protection and compliance?
Bonding protects you from two specific financial disasters: a contractor who walks off the job and a contractor who leaves unpaid subcontractors behind. Unpaid subs can file mechanic’s liens against your property even if you paid the general contractor in full. A payment bond eliminates that exposure.
Bonding signals contractor financial and operational discipline. A surety company does not issue a bond without reviewing the contractor’s financials, credit history, and track record. That review functions as independent due diligence on your behalf. When a contractor carries a bond, a third party has already vetted them.
A common misconception is that bonds replace contractor insurance. They do not. Insurance covers accidental damage and liability. A bond covers intentional or negligent failure to perform. You need both on any serious project. Warranties add a third layer of protection for workmanship after the job is done.
Owners who skip bonding on mid-size jobs risk significant financial loss if a contractor defaults. The premium cost of a bond is small compared to the potential exposure. Treating bonding as optional on a $50,000 kitchen remodel is a risk most investors would not accept in any other context.
- Bonds protect against contractor default and project abandonment.
- Payment bonds shield you from mechanic’s liens filed by unpaid subcontractors.
- Bonding verifies contractor credibility through third-party surety underwriting.
- Bonds do not replace insurance or warranties. All three serve different functions.
- Private projects are not legally required to carry bonds, but requiring them is sound risk management.
Pro Tip: Always ask a contractor for a copy of their bond certificate before signing any contract. Call the surety company directly to confirm the bond is active and covers the full contract value.
How does contractor bonding work?
The three-party structure is the foundation of how bonding works. The contractor applies to a surety company, which underwrites the bond like a line of credit. The surety evaluates the contractor’s credit score, financial statements, work history, and current backlog before issuing the bond. Surety underwriting expects zero claims and differs fundamentally from insurance underwriting, which prices in expected losses.
The cost of a surety bond
Bond premiums range from 1% to 10% of the bond amount, depending on the contractor’s credit and financial health. A $20,000 license bond costs $200–$2,000 per year. A $150,000 performance bond costs $1,500–$15,000 annually. Contractors with strong credit and clean financials pay rates at the low end of that range.
What happens when a claim is filed
A bond is a guarantee, not a gift. If a contractor defaults and the surety pays a claim, the surety pursues the contractor for full reimbursement. That is why bonding is called a credit instrument. The surety is not absorbing the loss. It is fronting the money and collecting it back from the contractor.
Bond claim resolution often delays projects 4–9 months even when the bond pays out. Bonding caps your financial damage. It does not prevent project disruption. Plan for delays if a default occurs, regardless of bond coverage.
Here is the typical sequence when a contractor defaults on a bonded project:
- The owner notifies the surety of the contractor’s default in writing.
- The surety investigates the claim and reviews the contract terms.
- The surety selects a remedy: financing project completion, hiring a replacement contractor, or paying damages up to the bond amount.
- The surety pursues reimbursement from the defaulting contractor.
- The owner receives compensation or project completion, subject to the bond limit.
Pro Tip: Apply for bonding well before you need it. Last-minute bond requests nearly always cause delays or denial because surety underwriting takes time. Contractors who establish a bonding program in advance win more bids and avoid project delays.
How to use bonding knowledge when hiring contractors
Verifying a contractor’s bond status takes less than ten minutes and can save you from a costly mistake. Ask every contractor you interview for their bond certificate, bond amount, and the name of their surety company. Then call the surety directly to confirm the bond is current and covers your project type.
Requiring a performance bond in a private renovation contract is not standard practice for small jobs, but it is worth the conversation on any project over $25,000. The bond premium is typically built into the contractor’s bid. You are not paying extra out of pocket. You are simply requiring the contractor to carry the cost of a guarantee they should already have.
Bonding serves as effective due diligence beyond financial health alone. A bonded contractor has passed a third-party review of their operations, not just their license. That distinction matters when you are comparing bids from contractors with similar prices but different levels of accountability. Use the vetting checklist for homeowners to build bonding verification into your standard hiring process.
Bonding works best when it is part of a broader protection strategy. Pair it with the right insurance coverage and a written warranty to cover all three risk categories: performance failure, accidental damage, and post-completion defects.
- Request the bond certificate and surety contact before signing any contract.
- Confirm the bond amount covers at least the full contract value.
- Ask whether the bond covers both performance and payment obligations.
- Include a bonding requirement clause in your written renovation contract.
- Check for contractor red flags that suggest a contractor may not qualify for bonding.
- Weigh the bond premium cost against your total financial exposure on the project.
Key takeaways
Contractor bonding is a three-party surety guarantee that protects project owners from financial loss due to contractor default, unpaid subcontractors, and incomplete work.
| Point | Details |
|---|---|
| Bonding is a credit instrument | A surety backs contractor performance; the contractor repays any claim the surety pays out. |
| Three bond types cover different risks | Bid, performance, and payment bonds each protect a distinct phase or obligation in a project. |
| Miller Act sets the federal standard | Federal projects over $150,000 require performance and payment bonds by law. |
| Premiums range from 1% to 10% | A $150,000 performance bond costs $1,500–$15,000 annually based on contractor credit. |
| Bonds do not prevent delays | Claim resolution takes 4–9 months on average; bonding limits financial damage, not project disruption. |
What I’ve learned about bonding after years of renovation work
Most homeowners treat bonding as a checkbox. They ask “are you bonded?” and accept “yes” as a complete answer. That is the wrong approach. The bond amount matters as much as the bond’s existence. A contractor bonded for $10,000 on a $90,000 addition leaves you exposed for $80,000 if something goes wrong.
The other thing I see constantly is owners conflating bonding with insurance. They are not interchangeable. Insurance pays for accidents. A bond pays when a contractor fails to perform on purpose or through negligence. You need both, and you need to verify both separately before a project starts.
Bonding also tells you something about the contractor’s financial discipline that a license check does not. A surety company reviewed that contractor’s books, credit, and track record before issuing the bond. That review is worth more than a reference call in many cases. A contractor who cannot get bonded is telling you something important about their financial health.
The limitation I always remind clients about is the delay factor. Even with a solid performance bond, a default means months of disruption before the surety resolves the claim. Bonding is not a fast fix. It is financial protection, not a guarantee of a smooth project. The best use of bonding knowledge is to select contractors who are unlikely to default in the first place, and then use the bond as a backstop, not a primary strategy.
— Brandon
Spudmetrix can help you build the right project protections
Knowing what contractor bonding means is only useful if your contracts actually require it. Spudmetrix helps Houston homeowners and investors put that knowledge into practice with remodeling contracts built for 2026 that include bonding requirements, payment terms, and protection clauses written in plain language.
Every Spudmetrix project starts with a free in-home consultation and a detailed written estimate. No vague pricing, no missing clauses. If you are planning a renovation and want a contract that covers bonding, insurance, and warranty requirements from day one, Spudmetrix is the place to start.
FAQ
What does contractor bonding mean in simple terms?
Contractor bonding is a financial guarantee from a surety company that a contractor will complete a project and pay all subcontractors and suppliers. If the contractor fails, the surety pays damages up to the bond amount.
Is a bonded contractor the same as an insured contractor?
No. A bond covers failure to perform or pay. Insurance covers accidental damage and liability. Both protect you in different ways, and you should require both on any significant project.
How do I verify that a contractor is bonded?
Ask the contractor for their bond certificate and the surety company’s name, then call the surety directly to confirm the bond is active and covers your project’s contract value.
Are performance bonds required on private renovation projects?
The Miller Act requires performance and payment bonds on federal projects over $150,000, and most states have similar rules for public works. Private renovation projects have no legal bonding requirement, but including one in your contract is sound risk management.
How much does a contractor surety bond cost?
Bond premiums range from 1% to 10% of the bond amount based on the contractor’s credit and financial history. A $150,000 performance bond costs between $1,500 and $15,000 per year.